New Zealand Rental Vehicle Market Insights Report: July 2019
MarginFuel’s report summarises the Average Market Rate of the New Zealand Rental Car Market for July 2019, showing key vehicle categories and locations.
July 2019
9th Edition | Issued 1 st August 2019
- Section 1 - July 2019 Analysis
- Section 2 - Year to Date (YTD) Analysis
- Section 3 Forward Market Analysis
- Methodology & Disclaimer
SECTION 1
JULY 2019 ANALYSIS
SECTION 1 - July 2019 Analysis
Year on Year (YoY^) Average Rate Change
- For all three locations, across all sales channels, there was an overall YoY average rate increase of +5%
- As is the typical winter seasonal trend, average rates for South Island Airports are higher than Auckland
- Christchurch Airport (CHC) had a YoY average rate increase of +11%
- Queenstown (ZQN) had a YoY average rate increase of +6%
- Auckland Airport (AKL) had a YoY average rate increase of +2%
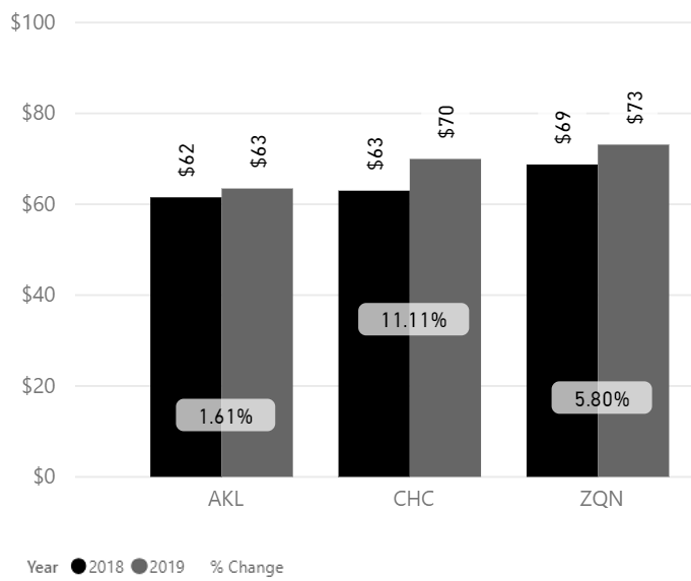
Fig. 1
SECTION 1 - July 2019 Analysis
Channel, Duration and Vehicle Category
Refer to sales channels (Fig.2), duration (Fig.3) and vehicle category (Fig.4) graphs for the average rates in July 2019. As is seasonally expected, average rates for SUVs from Christchurch and Queenstown Airports are higher than Auckland. As was the trend in June 2019, average rates for the shorter 3-day duration remains very strong.
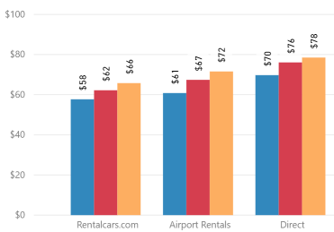
Fig. 2
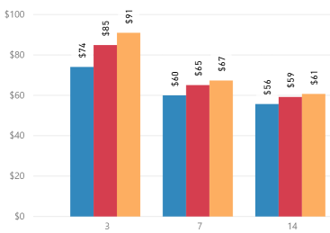
Fig. 3
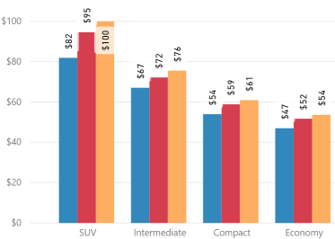
Fig. 4
SECTION 1 - July 2019 Analysis
Auckland Airport YoY Summary
Overall Auckland Airport had a YoY average rate increase of +2%.
Rentalcars.com sales channel showed an average rate decrease of -8%, while Airport Rentals and the direct channels showed increases of +3% and +13% respectively (Fig. 5).
The average rate for 3-day duration increased +9%, while the average rate for longer 7-day was flat, and 14-day duration; -2% (Fig. 6).
The average rate for SUVs in Auckland +1% YoY, with all other categories showing average rate increases of between +2% and +7% (Fig. 7).
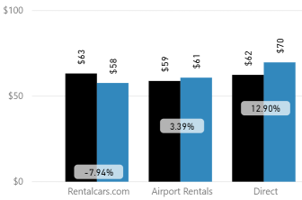
Fig. 5
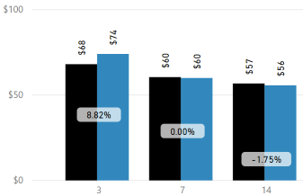
Fig. 6
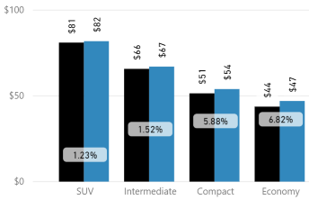
Fig. 7
SECTION 1 - July 2019 Analysis
Christchurch Airport YoY Summary
Overall Christchurch Airport had a YoY average rate increase of +11%.
Rentalcars.com sales channel showed an average rate decrease of -5%, while Airport Rentals and the direct channels showed increases of +14% and +19% respectively (Fig. 8).
The average rate for 3-day durations increased +18%, while the average rate for longer 7-day and 14-day durations increased by +7% and +4% respectively (Fig. 9).
The average rate for SUVs was up +12%, with all other categories increasing between +6% and +21% (Fig. 10).
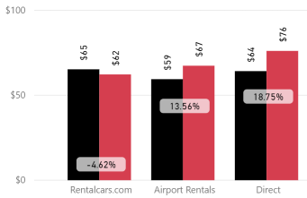
Fig. 8
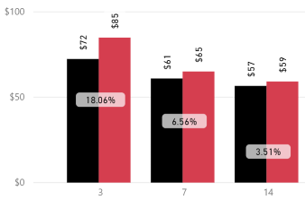
Fig. 9
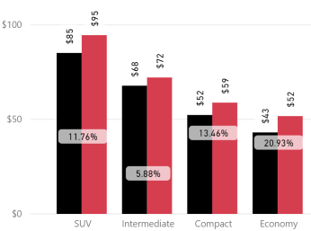
Fig. 10
SECTION 1 - July 2019 Analysis
Queenstown Airport YoY Summary
Overall Queenstown Airport had a YoY average rate increase of +6%.
The rentalcars.com sales channel showed an average rate decrease of -6%, while Airport Rentals and the direct channels showed increases of between +9% and +11% respectively (Fig. 11).
The average rate for a 3-day duration increased +14%, while the average rate for longer 7-day and 14-day +2% and flat respectively (Fig. 12).
The average rate for SUVs was up +3%, with all other categories increasing between +7% and +15% (Fig. 13).
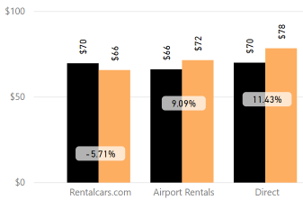
Fig. 11
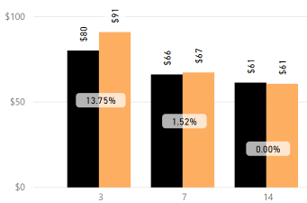
Fig. 12
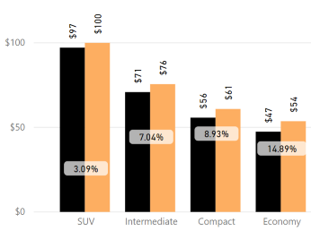
Fig. 13
SECTION 2
YEAR TO DATE (YTD) ANALYSIS
FROM APRIL TO JULY 2019
SECTION 2 Year to Date (YTD) Analysis
April to July 2019
- From April 2019 the average rates dropped as is the norm post peak as the market flows into the winter season (Fig.14)
- Averages rates started to strengthen in July 2019 as the winter season hits its mid point
- The average rate for Auckland Airport was consistent between May and July 2019, while both Christchurch and Queenstown Airports showed gains through that period
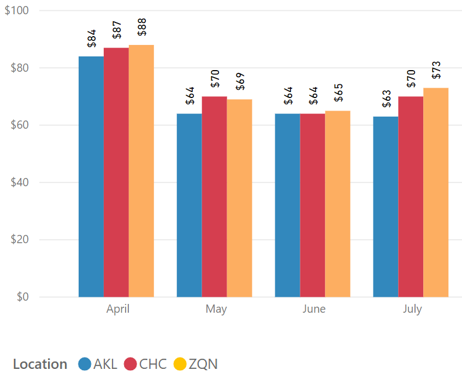
Fig. 14
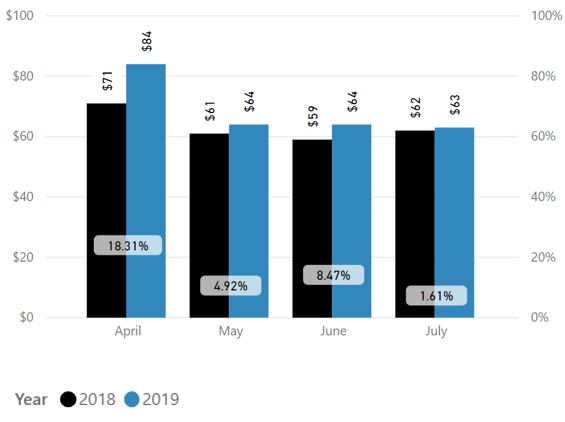
Fig. 15
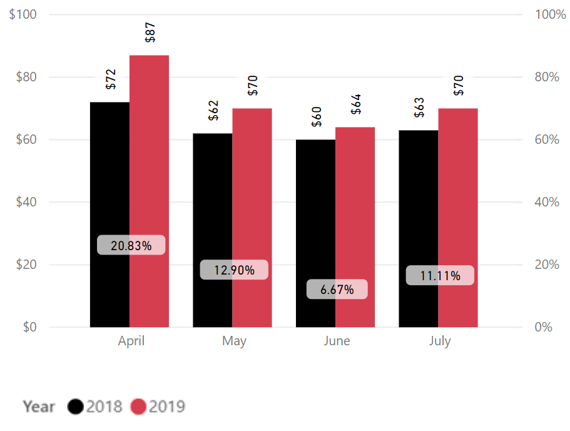
Fig. 16
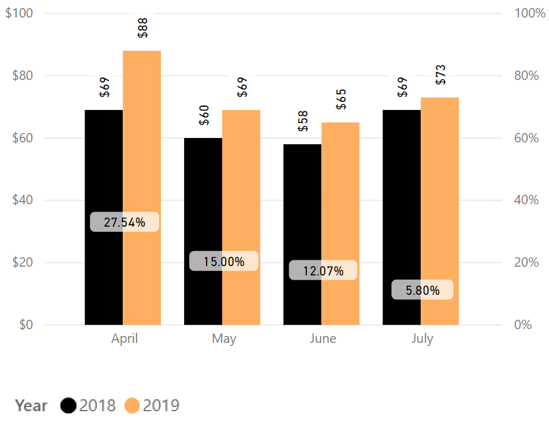
Fig. 17
SECTION 3
FORWARD MARKET ANALYSIS
FROM AUGUST TO DECEMBER 2019
SECTION 3 Forward Market Analysis
August to December 2019
Overall average rates for the coming months remain variable. For August the trend is above prior year, however as noted in last month’s report there is a potential YoY soft spot between September to November 2019 (Fig.18). The early average rate build for December 2019 is encouraging, however, those rates will firm up from November. The overall trend is consistent for all three locations (Fig.20 to Fig.21).
Market Insider Tip:
As the midpoint of the winter season is upon us the focus squarely remains on servicing South Island demand, with fleet mix remaining top of mind.
Early pricing suggests August 2019 will remain fairly stable but plan now for a period of YoY weakness between September and November 2019.
However, keep one eye on the Auckland build profile late in the winter season to ensure fleet is on hand in Auckland to service upcoming demand.
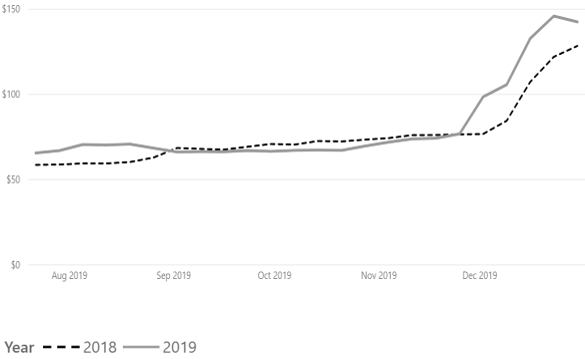
Fig. 18
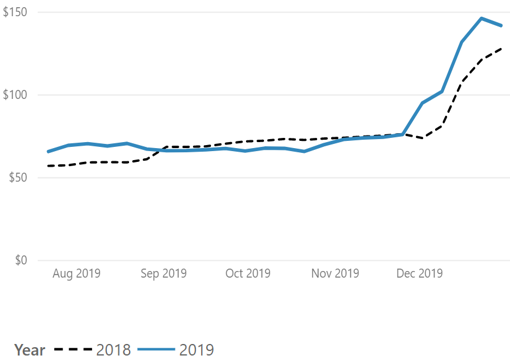
Fig. 19
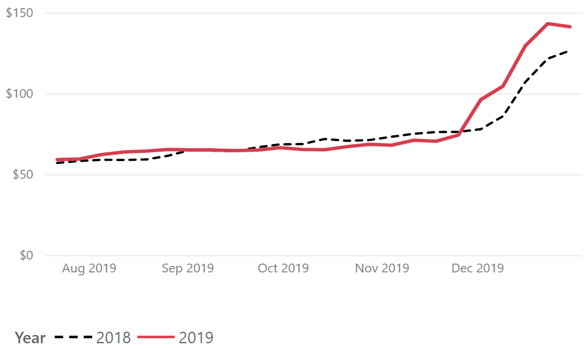
Fig. 20
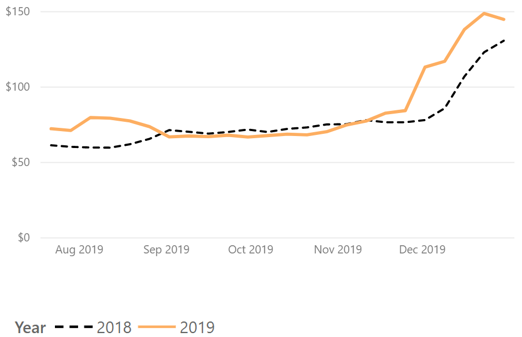
Fig. 21
Methodology & Disclaimer
Methodology:
- The data was derived from circa. four (4) million datapoints, and this size dataset was deemed large enough to draw reasonable conclusions
- Inconsistent outlying datapoints were removed
- The data collected is from 13 individual rental vehicle operators (a mix of independent, franchise, small, medium and large operators)
- The data collected from the 13 rental vehicle operators has been anonymised and aggregated, then displayed to provide a general reflection of the overall market
- The pickup days included in the data are Tuesdays and Fridays
Disclaimer: